How to Compare Trade-In and Purchase Options
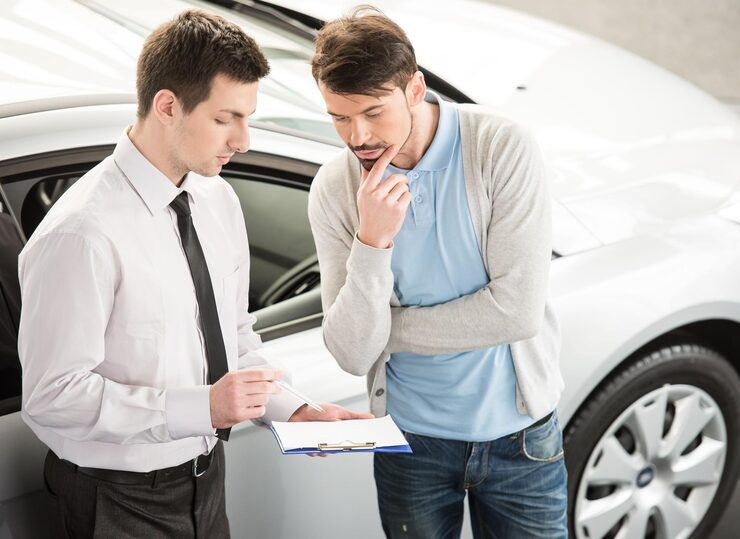
Trading in an existing vehicle while purchasing another can simplify the car-buying process, but it also creates several numbers that need to be compared carefully. The trade-in value, purchase price, financing costs, taxes, fees, and any remaining loan balance can all affect the final amount you pay. Buyers researching their options through car dealers Victoria TX can make the process easier by evaluating each part of the transaction separately before considering the overall deal. Rather than focusing only on the monthly payment or advertised trade-in allowance, it is useful to compare the complete financial picture and understand exactly what each option means.
Determine Your Current Vehicle’s Value
Before discussing a trade-in, research what your current vehicle may be worth. The value can depend on its make, model, year, mileage, condition, equipment, accident history, and local market demand.
The Federal Trade Commission recommends researching trade-in values through established automotive pricing resources before negotiating with a dealer.
Gather information about your vehicle, including its mileage, trim level, optional equipment, maintenance history, and overall condition. Comparing several valuation sources can give you a useful range rather than relying on a single estimate.
Remember that an online valuation is an estimate. A dealer will also consider the vehicle’s condition, inspection results, reconditioning needs, and marketability when determining a trade-in offer.
Calculate What You Still Owe
If you are still financing your current vehicle, find out the exact payoff amount before negotiating. The amount you owe may be different from the balance shown on a recent statement because interest and other factors can affect the payoff figure.
Compare the payoff amount with your vehicle’s estimated market and trade-in values. If the car is worth more than the amount you owe, you have positive equity. That equity can potentially be applied toward your next vehicle.
If you owe more than the vehicle is worth, you have negative equity. The FTC explains that negative equity can sometimes be included in the financing for the replacement vehicle, increasing the amount borrowed and potentially the overall interest cost.
Get the Purchase Price Separately
One of the most useful ways to compare a trade-in and purchase transaction is to separate the numbers.
First, determine the price of the vehicle you want to purchase before factoring in your trade-in. Ask for the out-the-door price in writing, including applicable taxes, fees, and other charges.
The FTC recommends obtaining an out-the-door price before visiting a dealership or discussing financing because it makes it easier to compare offers and identify additional charges.
Once you know the purchase price, you can evaluate the trade-in offer separately. This prevents a high trade-in allowance from distracting you from a higher purchase price.
Compare Trade-In Offers
A trade-in offer should be evaluated against the actual market value of your vehicle, not simply whether the number looks large.
For example, one dealer might offer a higher trade-in allowance but charge more for the replacement vehicle. Another might offer a lower trade-in amount but provide a lower purchase price. Comparing the two numbers independently can reveal which transaction structure is more favorable financially without relying on a single headline figure.
The FTC specifically advises consumers to negotiate the purchase price before discussing the trade-in so that the numbers are easier to evaluate independently.
Understand Positive Equity
Positive equity occurs when your vehicle is worth more than the amount you owe on its loan. For example, if your car is worth $20,000 and your payoff amount is $14,000, you have approximately $6,000 in equity.
That equity may be applied toward the next vehicle as part of the transaction. A larger effective down payment can reduce the amount that needs to be financed.
However, buyers should still compare the purchase price and financing terms independently. Equity does not automatically make a vehicle purchase less expensive if the replacement vehicle itself is priced higher than expected.
Understand Negative Equity
Negative equity requires additional attention. Suppose your current vehicle is worth $15,000 but you owe $18,000. The $3,000 difference does not disappear when you trade the vehicle.
The FTC warns that negative equity can be rolled into a new auto loan in some transactions. This increases the amount financed and means you may pay interest on the carried-over balance as well as the replacement vehicle.
Ask the dealer to show exactly how any remaining balance is being handled. Review the financing agreement carefully before signing and confirm the amount being financed.
Compare Financing Offers
Once the purchase and trade-in values are understood, compare financing terms. Look beyond the monthly payment and examine the annual percentage rate, loan term, down payment, amount financed, and total finance charges.
The FTC notes that a lower monthly payment can result from a longer loan term, potentially increasing the total amount paid over time.
Getting preapproved through a bank or credit union can also provide a useful benchmark. You can then compare that offer with dealer-arranged financing.
Look at the Total Cost
The most useful comparison is the total amount you will spend rather than one individual figure.
Consider the purchase price, trade-in value, remaining loan balance, taxes, registration costs, dealer fees, financing charges, optional products, and expected ownership expenses.
For example, a vehicle advertised with a low monthly payment may still cost substantially more over a longer financing period. Similarly, a large trade-in allowance may not provide much benefit if the replacement vehicle carries a significantly higher price.
Be Careful With Add-Ons
Optional products can change the final cost of a transaction. These may include service contracts, gap coverage, vehicle protection products, and other dealer-offered items.
The FTC advises consumers to ask how much each add-on costs and what it provides before agreeing to purchase it.
If an add-on is not part of your original plan, ask whether it is optional and request an updated written breakdown of the transaction without it. This makes it easier to determine the actual cost of the vehicle.
Consider Selling Privately
Trading in a vehicle is convenient, but selling privately is another option. A private sale may potentially produce a different price because the transaction involves a direct buyer rather than a dealer acquiring the vehicle for resale.
However, private sales can require more time and effort. You may need to advertise the vehicle, respond to inquiries, arrange test drives, handle paperwork, and complete the transaction yourself.
Compare the estimated private-sale amount with the trade-in offer while considering the value of convenience and the time involved.
Inspect and Prepare Your Trade-In
Before requesting a trade-in appraisal, make sure you understand your vehicle’s condition. Gather maintenance records, remove personal belongings, clean the interior, and address inexpensive issues when appropriate.
Do not spend heavily on cosmetic improvements simply to increase the trade-in value without first considering whether the additional expense is likely to be recovered.
A dealer will generally evaluate the vehicle based on its overall condition, mileage, mechanical state, equipment, and market demand.
Compare Multiple Transactions
You do not have to compare only two numbers. If practical, obtain purchase and trade-in figures from multiple dealers.
Ask each dealer for the purchase vehicle’s out-the-door price and a separate trade-in value. Keeping these figures separate makes it easier to compare the actual structure of each offer.
Written offers can also reduce confusion when negotiating because you have a clear record of the numbers being discussed.
Review the Final Contract
Before signing, carefully compare the final paperwork with the figures you negotiated. Verify the vehicle price, trade-in allowance, payoff amount, down payment, financing terms, fees, optional products, and total amount financed.
The FTC recommends reviewing the terms carefully before signing and ensuring that promised terms and charges are accurately reflected in the agreement.
Do not rely solely on verbal explanations. If an important promise or adjustment is part of the agreement, make sure it appears in the written documents.
Conclusion
Comparing trade-in and purchase options requires looking at the entire transaction rather than focusing on a single number. Research your current vehicle’s value, determine the exact loan payoff, establish the replacement vehicle’s out-the-door price, and evaluate the trade-in allowance separately. Then compare financing terms, taxes, fees, add-ons, and the total amount financed. If you have negative equity, understand exactly how it will be handled before signing. Whether you trade in your vehicle or consider selling it privately, careful comparison can help you understand the true cost of changing vehicles and make the transaction easier to evaluate.